Storm damage in your area? Free inspection within 24 hours.
Demo site built by Roof Flow Sites

Insurance claims

Your claim, explained like you've never filed one.

Most homeowners file a roof claim once in their life. The carrier does it ten thousand times a day. This page is here to close that gap — read it even if you hire someone else.

Step by step

What happens, in order.

From your first call to the final check, here's the whole sequence and who does what.

  1. 01

    Free inspection

    We photograph every slope, mark test squares, and measure the hail impacts. You get the report whether or not you file.

  2. 02

    You file the claim

    We give you the date of loss, the damage summary, and the exact language to use. The call takes about ten minutes.

  3. 03

    We meet your adjuster

    We are on the roof with them, report in hand, so nothing gets missed and the scope is agreed on site.

  4. 04

    Supplements approved

    Code items, decking, and anything the first scope missed get submitted with documentation until the file is right.

  5. 05

    Build and final invoice

    One-day tear-off and install on most homes. You pay your deductible. The carrier pays the rest, including depreciation.

The four words that confuse everyone

Deductible, ACV, RCV, supplement.

Understand these and you can read your own settlement letter without calling anyone.

Deductible

Your share of the loss, set in your policy — usually a flat amount like $2,500 or a percentage of your dwelling coverage (1% of a $400,000 home is $4,000). It applies once per claim, not per trade. If the roof, gutters, and screens are all on the same claim, you pay it once. Nobody can legally waive it or 'eat' it for you in Texas, and any contractor who offers to is telling you how they treat paperwork generally.
ACV — Actual Cash Value

The replacement cost of your roof minus depreciation for the years it was already used. It's the first check the carrier sends, and it arrives before any work is done. On a ten-year-old roof it might be half of the total. This check is not the whole settlement, and it is not what the job costs.

RCV — Replacement Cost Value

The full cost to put the roof back, with no depreciation deducted. If you carry RCV coverage, the carrier releases the withheld depreciation — the 'recoverable depreciation' — after the work is completed and the final invoice is submitted. Do the work, submit the paperwork, get the second check. Skip the work and you keep only the ACV.

Supplement

A request to add something the first scope missed or priced wrong. Decking replacement, ice-and-water shield required by code, a second layer discovered at tear-off, steep or two-story access charges, drip edge. Supplements are normal, expected, and where an experienced contractor earns their keep — with photos, code citations, and line-item pricing.

The adjuster meeting

What actually happens that morning.

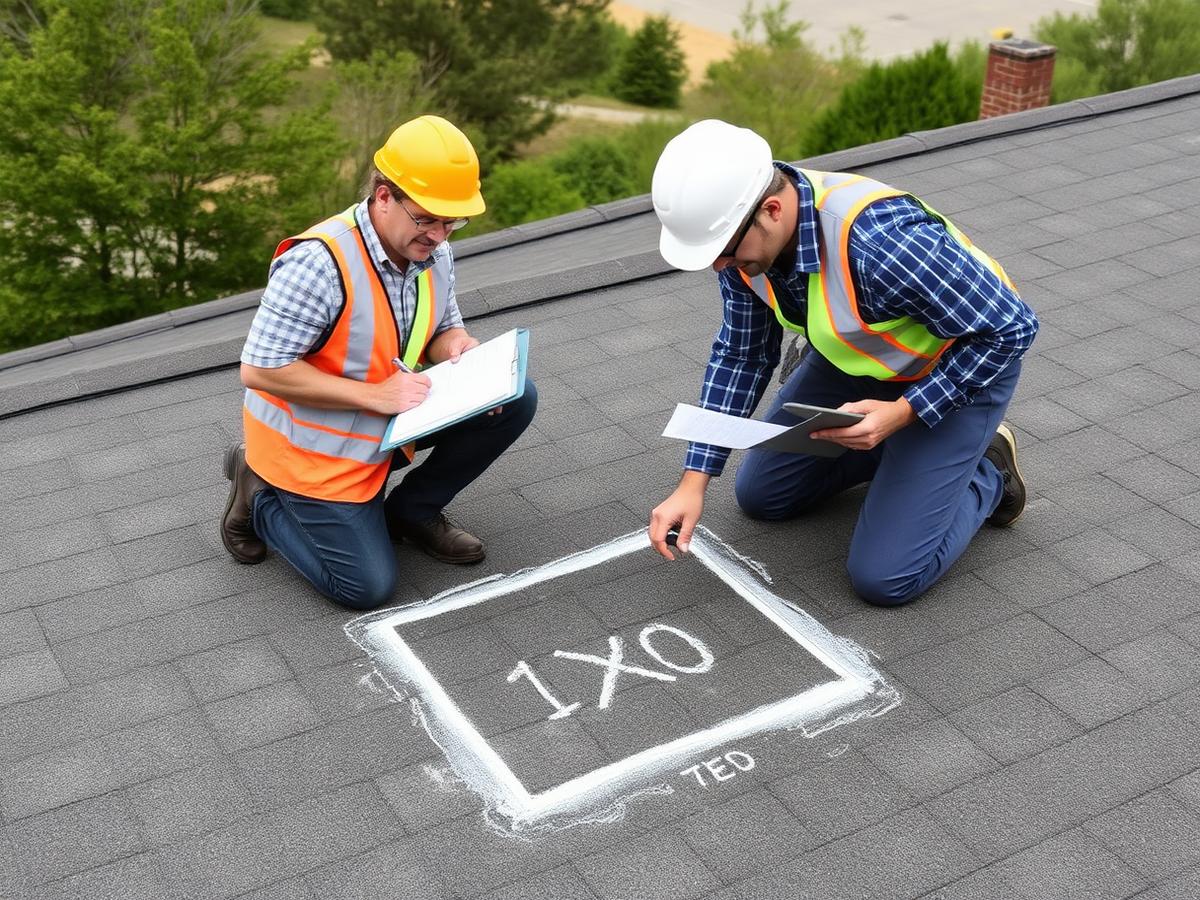
The carrier sends a field adjuster, often an independent contractor working several storms at once. He has a ladder, a chalk line, and about forty minutes. What he writes that morning becomes the scope of your entire job.

We meet him on site, every time. We go up together, walk the same slopes, and agree on the test squares before anything is written. Our inspection report is already in his hands, so the conversation is about scope, not about whether damage exists.

You don't need to be on the roof. You don't need to argue. Be home to let him in, and let the two people who do this for a living work it out in front of you.

A week or so later you receive a scope sheet and an ACV check. Send us the scope — all of it, including the summary pages. That document tells us what was approved, at what price, and what got left out.

contractor and field adjuster reviewing chalk-marked test square

What you pay, start to finish

  • Inspection: $0
  • Claim filing help: $0
  • Adjuster meeting: $0
  • Supplement negotiation: $0
  • Your deductible: due at completion

Everything above your deductible is paid by the carrier under your policy.

Next step

Bring us the storm date. We'll handle the rest of the file.

If you've already filed, send us the scope sheet and we'll tell you in a day whether it's short.